
Kantar Canada says marketers risk misreading consumer behaviour by leaning too heavily on engagement metrics in a market defined by limited choice, rising competitive pressure and increasingly fragmented media consumption.
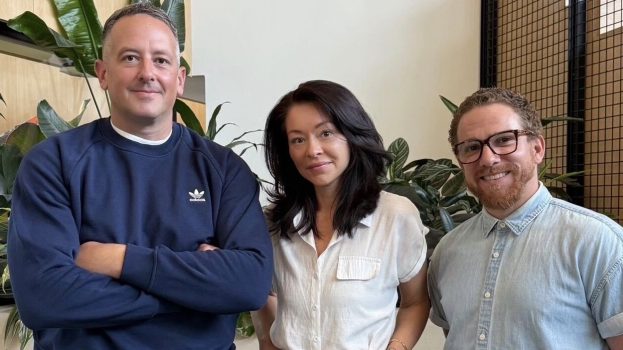
The perspective reflects work underway across the market research, data analytics and consulting company’s qualitative and media-measurement practices, where Kantar has been examining how constrained choice shapes consumer behaviour, and how that behaviour is often misinterpreted through engagement-led metrics. The thinking draws on insights from across both disciplines, including those led by Tim Kibbey, who has been with Kantar for 11 years and was recently named head of qualitative, and Brandon Kirk, who joined the firm in October as VP of growth and strategy, media measurement.
According to Kantar Canada, the combination of limited brand choice and platform-reported metrics can amplify false signals, encouraging marketers to overvalue activity while underestimating whether media exposure is actually shifting perception, preference or behaviour.
In a market like Canada, where consumers have fewer brand options, the margin for misinterpretation is smaller. Kirk says independent, cross-media measurement that links exposure to brand lift and business outcomes is increasingly critical, as high engagement does not necessarily indicate meaningful attention or effectiveness. For marketers, that means resisting the pull to chase volume or cultural relevance alone, and instead focusing on what genuinely builds brand meaning, preference and sustained growth.
Canadian marketers occasionally underestimate just how profoundly limited choice shapes the Canadian consumer psyche, Kibbey says. The result, he argues, is not just faster switching, but a market where weak differentiation is punished more quickly than in the U.S.
“We like to compare ourselves to the U.S., but the reality is stark: A market 10 times the size naturally breeds variety, experimentation and niche offerings,” Kibbey says. “Our marketplace is smaller, tighter and far more constrained.”
As Kibbey tells strategy, amid cross-border spats, featuring a maple leaf on a box might buy a brand a deserved moment of goodwill, but that’s a short-term mandate, not a strategy.
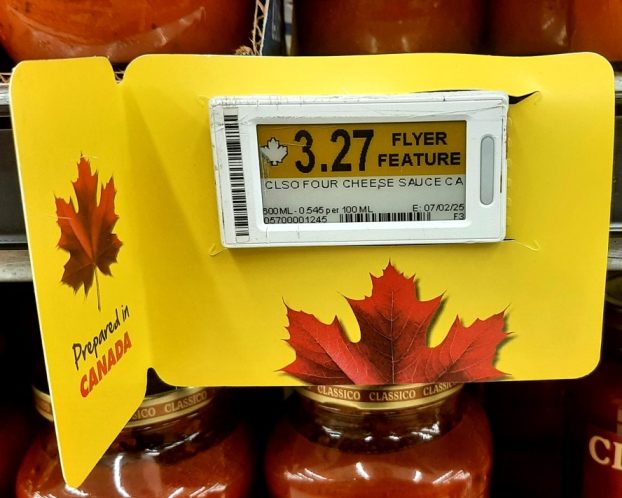
(Image credit: C. Lombardo)
“Canadians aren’t simply toggling between ‘avoid American’ and ‘buy Canadian,'” Kibbey explains. “Their desire for alternatives is accelerating because they’ve never had many to begin with. When an American shopper is choosing across 15-20 brands and a Canadian only has three or four, and prices jump across all of them, the hunt for new options isn’t just predictable, it’s inevitable.”
With new global trade deals in the works, global brands could soon be entering Canada and an appetite for novelty may mean homegrown brands need to act fast.
“Compounding this, as domestic trade barriers are broken down, designations such as ‘B.C. made’ and ‘Ontario grown’ will also introduce new competitive brands,” Kibbey says. “And the rise of hyperlocalism can complicate the story even further: Saying you’re Canadian is one thing; proving you’re rooted in someone’s actual community is quite another when it comes to looking for alternatives.”
Canadian brands should see this as an “alarm bell ringing loudly,” Kibbey stresses, because while national symbolism is important, it doesn’t replace the need for real differentiation, amid a milieu in which global brands are poised to enter with scale and sophistication.
Meanwhile, according to Kirk, engagement and social-listening platforms play an important role in capturing consumer signals such as mentions, shares, clicks, sentiment and conversation. This is where measurement shortcuts begin to influence not just media plans, but brand decisions themselves, he adds.
“The challenge comes when those signals start to be used as a proxy for impact,” Kirk says. “Activity does not always equal influence, and high volume does not necessarily translate to meaningful attention or brand effect.”
According to Kirk, media engagement is about more than interaction. It should also encompass who was reached, in what context, with what creative quality and whether that exposure actually shifts perceptions or behaviour. Without understanding attention, environment and creative impact, it is easy to overvalue volume and undervalue effectiveness, he adds.
“That’s where the temptation to be everywhere comes from. When measurement is fragmented and platform reported, marketers can end up chasing the next culturally relevant channel rather than focusing on what truly works.”
Kirk points out that not all engagement is created equal and that in Canada, “there’s a clear shift toward independent, cross-media measurement that connects exposure to brand lift and business outcomes.”
That clarity, he says, can help marketers make confident decisions about where to show up, how often and with what message, based on evidence rather than hype. Ultimately, in a constrained market like Canada, Kantar argues that the risk isn’t under-exposure, it’s mistaking activity for progress, and optimizing brands toward noise rather than growth.