 While economic anxiety dominates the current conversation, one of the most important signals for marketers may be this: Canadian consumers haven’t stopped shopping. They’ve just changed how they decide.
That’s the central finding from Consumer Survey Insights: Q4 2025, conducted by Criteo, the global commerce media company focused on understanding how consumers move from discovery to purchase. Criteo’s research found that instead of a pullback, what’s unfolding is a shift toward longer decision cycles, deeper evaluation and increased reliance on digital touchpoints – even when the final transaction happens in-store. In practical terms, Canadians are spending more time on the journey before they spend money.
According to the report, financial sentiment in Canada remains steady, with 37% of Canadians reporting their financial situation is unchanged from a year ago, while nearly equal shares say they feel better (23%) or worse off (20%). Spending intent across essential categories continues to hold, with 91% planning to spend the same or more on groceries in the coming months.
But purchases – particularly non-essentials – are increasingly delayed, as caution affects timing more than demand. “The situation is a little more nuanced,” says Florent Maillard, head of insights and analytics, global at Criteo. “Traffic is up. Consumers express an engagement and a willingness to purchase items in the future. But many parameters in the economy and news cycle are making them delay select purchases.”
That distinction reframes what reduced conversion may actually mean. Lower immediate spend does not necessarily signal declining interest. Instead, it reflects a longer consideration phase.
Criteo is seeing that consideration show up in the form of rising interaction with product-level content across retail ecosystems. “The proxy we look at is product page views across thousands of retailers,” Maillard explains. “In some retail categories, growth is double digit. Curiosity for products is way up.”
For marketers, this suggests that influence is shifting upstream. The battle is less about the final click and more about shaping the evaluation phase: the point where consumers are actively comparing, filtering and validating options.
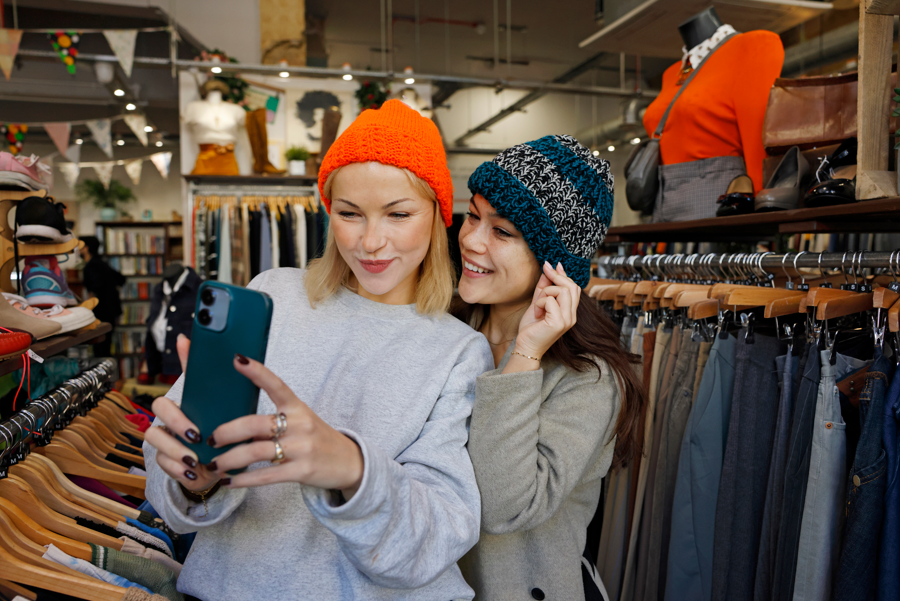
That’s also where the relationship between ecommerce and physical retail is becoming more tightly interwoven. Rather than competing channels, digital and in-store environments are operating as mutually reinforcing stages of the same journey. In Canada, 40% of shoppers say they research online before buying in-store, while 23% do the reverse. Discovery and transaction are increasingly split across channels.
“It’s not new that online influences in-store,” notes Janine Flaccavento, managing director, Canada. “What’s different now is that we’re able to track that across multiple retailers, and we know that the overall effect is positive.”
Advertising is also part of that influence layer. In Canada, 39% of shoppers say they discover new brands through online ads, and 44% say they sometimes make an in-store purchase after seeing one. Social media advertising is particularly influential, with 50% saying it plays a role in driving offline buying behaviour. Ecommerce is no longer just a destination. It shapes perception, discovery and evaluation across the entire journey.
The same dynamic is now emerging in Canadians’ relationship with AI. Canada has historically lagged peer markets in ecommerce adoption. Yet Criteo’s research shows that when it comes to AI-assisted shopping, Canadians are aligning more closely with global behaviour than expected: 57% say they anticipate using AI to help inform purchase decisions in the coming year. “Canadians’ acceptance of agentic shopping is clearly influencing the consideration phase,” Flaccavento says. “The pace of awareness, interest and usage is rapid. And what’s most interesting is that it’s across almost all retail verticals, from grocery to fashion, and consumer electronics.”
Consumers are not just experimenting with AI; they are integrating it into their evaluation process, using it to compare options, surface value and reduce friction in decision-making. More than half are already using AI tools for research, with 41% turning to them to find the best prices or deals.
Crucially, AI is not simplifying the journey by replacing complexity: it’s helping consumers navigate it. Canadians continue to engage with multiple sources before purchasing, with most visiting one to three sites before making a decision, combining efficiency with discovery rather than prioritizing one over the other.
“Consumers still use multiple channels. Complexity is still there. But they want more tools to navigate it,” Maillard says.
That’s particularly relevant in a market where loyalty is increasingly contingent on experience. In fact, 68% of Canadians say they have switched brands in pursuit of a better shopping experience, even as price remains a dominant consideration.
Yet convenience is not the only force shaping behaviour. National identity continues to influence purchase decisions, with 74% of Canadians saying “Made in Canada” messaging resonates with them. Even as discovery becomes globalized and algorithm-driven, alignment with local values remains a differentiator.
For marketers, the takeaway is not simply that Canadians are cautious. It’s that the path to purchase is expanding, creating more moments where influence can occur. Shoppers move naturally between online research, in-store browsing, advertising exposure and AI-assisted evaluation. What marketers might organize as separate media and commerce channels is, for consumers, a single continuous journey.
In that setting, success doesn’t come down to intercepting demand at the moment of transaction, but rather, shaping how decisions are formed along the way. The Canadian consumer has not withdrawn from the market. They have become more deliberate within it.
Explore Consumer Survey Insights: Q4 2025 for the full report on how Canadian shoppers are reshaping the path to purchase.