Madison and Wall has raised its 2026 Canadian advertising growth forecast to 5.8%, even as economic uncertainty and policy pressures are expected to temper momentum from last year’s stronger performance. The revised outlook, up from 5.1%, reflects stable underlying conditions, though the U.S.-based consultancy warns that structural headwinds will weigh on marketing investment throughout the year.
The advisory and consulting firm reports that the Canadian economy remains stable despite those headwinds. While the economy slowed in Q4, Canada’s nominal GDP growth cooled to around 3.3% year-over-year, down from the 3.9% growth seen in the previous two quarters.
“Inflation remains contained, with [the Consumer Price Index (CPI)] at 2.2% and core CPI near 2.5%, broadly in line with the Bank of Canada’s target,” Friday’s report states. “Businesses and consumers continued to navigate elevated trade volatility with the United States while Canada pursued efforts to diversify its economic partners. Against this backdrop of uncertainty through 2025, investments in marketing and advertising faced structural headwinds, a dynamic likely to persist in 2026 even as underlying consumer and economic conditions remain stable.”
Madison and Wall forecasts growth to be stronger in the first half of 2026, as economic uncertainty and policy developments weigh on marketing budgets.
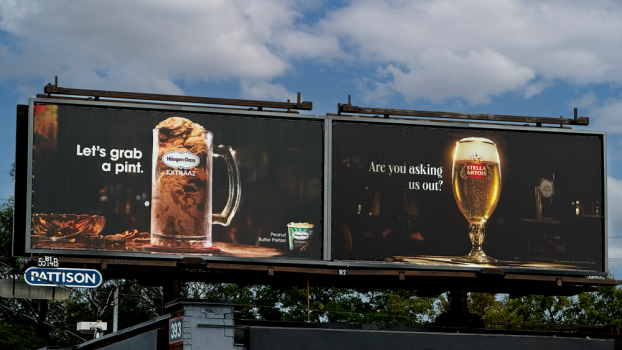
Outdoor advertising is expected to experience “modest growth, increasing by 4% year-over-year.” One catalyst, according to the report, will be the 2026 FIFA World Cup, with Canada hosting 13 matches in Toronto and Vancouver during the summer. “A large global event such as this one will likely provide a temporary boost to out-of-home advertising demand,” Madison and Wall says.
Within the market, commerce media is again projected to be the fastest-growing major channel, with Madison and Wall expecting advertising revenues to increase 14% year-over-year, followed by social media (12%) and search advertising (5%).
The advertising economy grew by 11.4% year-over-year in Q4, reaching $27.4 billion for the full year 2025. Q4 represented the fastest growth of the year, ahead of the Q1 rate of for 2025 (10.9%), as the global economy continued to expand through the end of the year despite rising concerns around trade uncertainty, labour supply and energy-related inflation pressures. “By channel, growth was led by commerce media, which increased 26% year-over-year in Q4 2025,” Madison and Wall reports. “Unsurprisingly, Amazon led the category and represented roughly 80% of total commerce advertising revenues in the quarter. Growth was broad-based, however, with strength across traditional brick-and-mortar retailers as well as grocery, electronics and other e-commerce sectors.”
Growth in commerce media, social media and search advertising
Commerce media in Canada continues to benefit from several structural factors, the firm said, including the shift to online shopping, access to premium and privacy-safe first-party data, the ability to measure advertising directly against purchases and business outcomes and the “pay-to-play” model used by most retail-media networks.
Social media was the second-fastest growing channel in Canada, increasing 21% year-over-year, with AI-powered tools improving both ad execution and content recommendation. “In Canada there continues to be an ongoing dispute between digital platforms and publishers over news content distribution, although recent commentary by Prime Minister Mark Carney suggests a possible resolution in 2026,” Madison and Wall says, adding that many news organizations have pivoted toward direct distribution through their own platforms and owned-and-operated channels.
Search advertising rounded out the fastest-growing major channels, increasing 12% year-over-year. Search and social media are now roughly equal as the largest components of the Canadian advertising market, generating approximately $7.4 billion and $7.2 billion respectively in revenue during the fiscal year 2025. Digital advertising in aggregate represented 77% of total advertising budgets in Q4, rising from 73% a year ago, the report states.
“Outside of digital platforms, in Q4 2025 television (including connected TV) declined 6% while print (including publishers’ digital extensions) fared slightly better at negative 1% year-over-year,” Madison and Wall says. “While negative, both represented a slower pace of decline compared with Q3 2025, a quarter featuring difficult comparables because of the 2024 Paris Olympics. Within television, we estimate that CTV was strong (up 13% in Q4 2025), implying a worse outcome for linear TV (down 9% for the quarter).”
Regulatory developments shaping Canadian market
Regulatory developments are also shaping Canada’s video marketing, including the Canadian Radio-television and Telecommunications Commission’s Online Stream Act. In Q4, the act was further defined, clarifying what qualifies as Canadian content. A future ruling will determine the financial contribution requirements for streaming platforms. “The classification of Canadian content in this context is important because it unlocks tax credits, access to Canada Media Fund support and eligibility for future streaming levy funds (if it makes it through current legal challenges), while also helping companies meet Canadian content production quotas,” the report says.
The updated rules represent another step toward the goal of Canadian regulators and domestic media companies, which have been seeking to direct more spending toward Canadian content and ad inventory. “With that noted, we expect global digital platforms to maintain their advantage with marketers due to economies of scale, convenience, advantages in distribution and data and other factors,” Madison and Wall says. “Regulation may narrow the capability and competitive gap somewhat over time, but structural advantages for digital platforms remain significant. However, a focus toward Canadian media spending is visible in parts of the industry.”
WPP Canada recently reported that 45% of its total media spending now goes to Canadian media owners, with a target of 50% by 2026. The natural skew of large brands toward television – which, by virtue of regulation, means that spending is necessarily directed to Canadian media owners and not necessarily to Canadian content producers – drives the large share allocation.